The cap stays on
I wore a new cap to the office on Monday. Blue, with a wall of text emoticons stitched across the front. A few people at Merantix AI Campus asked where it came from. I told them: from a room full of people who run agents in production, not in slide decks.
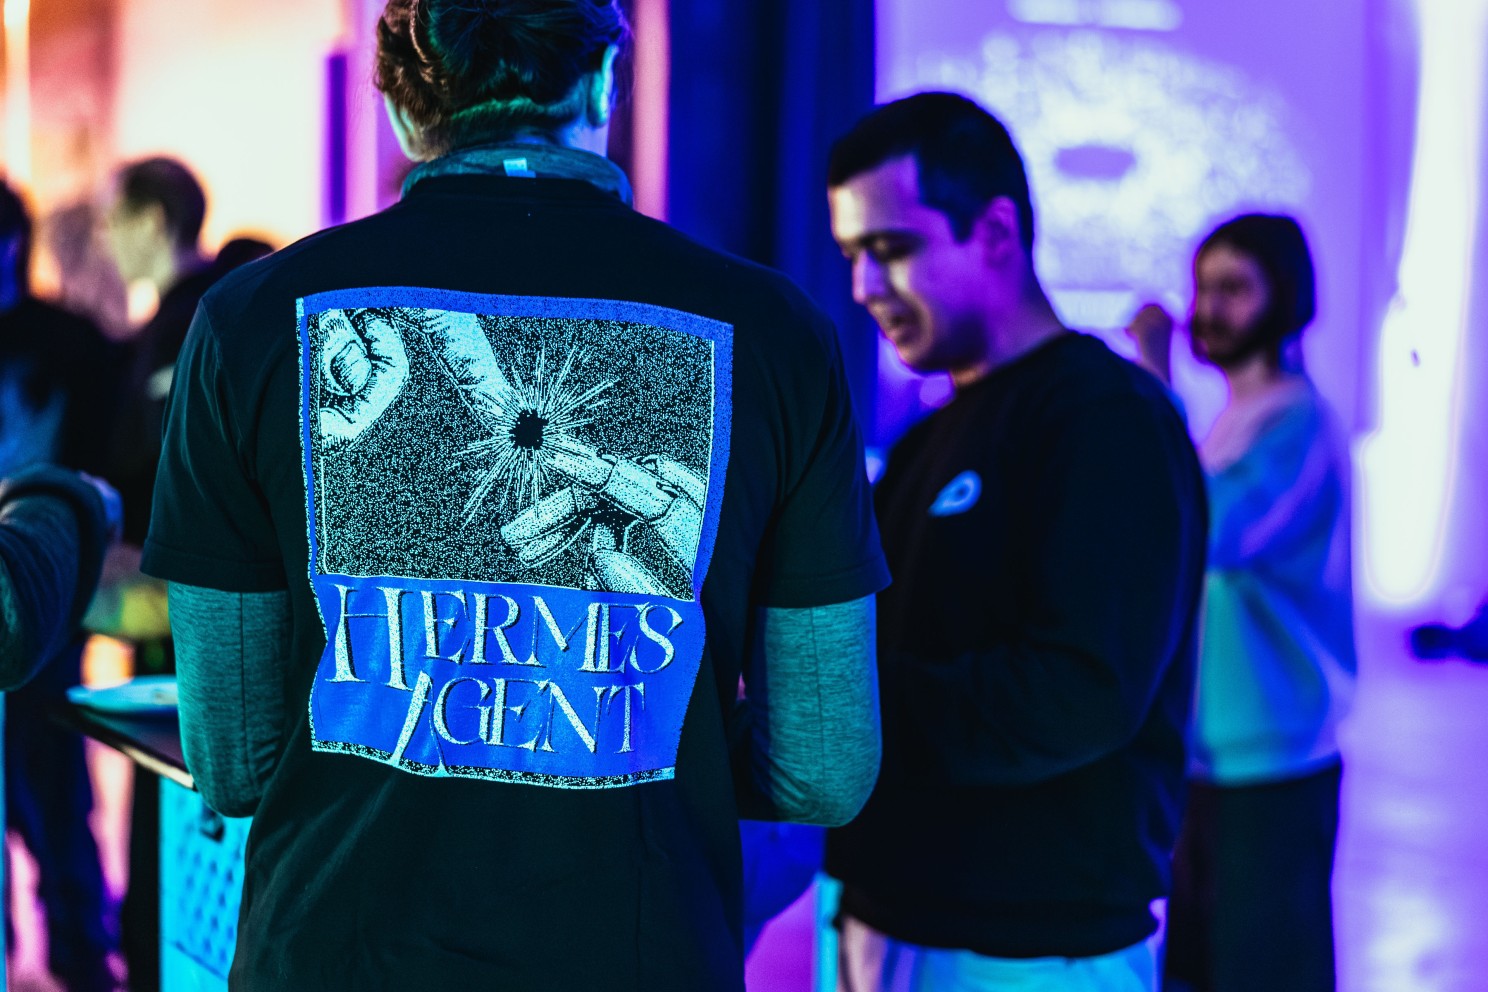
Last week, Circuit Berlin hosted the Hermes Agent Power Users Meetup, by Nous Research. Laptops open on every high table. Cameras rolling. Hermes shirts everywhere. Nobody pitched anything. People opened their terminals and showed what they had built, what broke, and how they fixed it. I spent an hour arguing about bots, tool calls and local models with people I had never met, under lighting that changed color every ten minutes.
That is what a community should be. Builders comparing scars. Playing ping pong on the 5th floor to close the day. Thank you, Circuit. The vibe was right. The cap is now part of the uniform.
Most companies are still exploring. Some are already moving.
Most organizations are still “exploring AI.” Pilots, steering committees, a working group on the future of work. Twelve months later they have a policy document and zero changed processes.
Agentic organizations do something simpler and harder. They redraw who does what. Agents gather, sort, cost and measure. Humans hold the gates: what gets built, and whether it worked. Everything in between is either automated or deleted.
That split is the whole game. Companies that make it will run faster every quarter, because every release teaches the system something. Companies that don’t will keep hiring people to move data between spreadsheets.
We are rebuilding Solution Management at Primion on that split.
How Hermes fits
Hermes is an operating layer. Agents pull the signals: customer requests, support tickets, tech debt flagged by engineering, usage data from the field. They turn that pile into a ranked backlog and put three things next to every option: what it costs, how fast it reaches customers, and what it should move.
Then a human decides. Then agents track what the release actually did, and that result feeds the next cycle.
The part I care about most: R&D works from the same backlog via Atlassian stack. Same scoring, same gates, same evidence. No translation layer between solution management and engineering. No requirements thrown over a wall. When an agent flags tech debt, it competes in the same ranking as a customer request, scored the same way. Priority debates got short, because the evidence is on the table before anyone walks into the room.
We don’t marry one model. At this moment, some cloud agents handles the heavy reasoning: synthesis, specifications, pricing scenarios, anything that has to survive a customer reading it. Then other local models, no tokens, narrow tasks where the data stays in the building, like classification, tagging and first-pass triage of internal material. In security, where the data lives is a decision you don’t hand to someone else. Right model, right job, right location.
The result: backlog preparation that used to eat a week of my team’s time now takes minutes. The people I have now spend their time on judgment, not on gathering.
The question nobody wants to answer: pricing
Agents break the seat. If software completes the work, counting the humans who log in is the wrong meter.
I have made this switch once before, in hardware. We sold a machine, installed it, and then waited years for the replacement cycle. One sale, one invoice, then silence. We added a micro-transaction model on top and charged a fee for every transaction the machine handled. The customer paid for the work, not only the box.
Everyone celebrated the recurring line in the results. The real shift happened in sales. A per-transaction fee does not fit a compensation plan written for a capital sale. It does not fit a forecast built on units shipped. We solved it by running the new model as a parallel business with its own team, its own plan and its own numbers.
The price change was the easy part. The sales motion was the hard part. Software is about to learn the same lesson.
On July 22, ServiceNow reported its second quarter. Subscription revenue up 24.5%. AI annual contract value past $1bn. Bill McDermott, whom led SAP when I was there, had already told analysts that half of net new business is non-seat-based. Gina Mastantuono ono put the principle more plainly than any vendor deck: customers are not paying for tokens, they are paying for resolutions. AI that only advises is a cost. AI that completes the work is a return.
Now look at the rest of the market. Benchmarkit found 67% of SaaS companies still don’t charge separately for AI. G2 surveyed more than a thousand software buyers in July: preference for outcome-based pricing doubled, from 11% to 23%, and 70% said the pace of AI is pushing them toward shorter contracts.
Do the math. Shorter contracts mean lower effective annual contract value. Acquisition cost does not fall with it. Payback stretches. The magic number slips. The sales motion becomes unaffordable about a year before anyone traces it back to a pricing decision.
That is why pricing is now a first-order management task. Not a finance footnote. Not something marketing sorts out at the next launch.
One ask
Work out what share of your net new business last quarter was priced on something other than a seat. Reply with the number. I will publish the range, anonymized.
The published benchmarks lag. I want to see what is actually happening in the market.
See you at the next meetup. I’ll be the one in the blue cap.
Let’s talk possibilities!
Every project on this page started with a conversation about a real operational challenge. Bring us yours, and let’s explore what a working prototype could look like.